Understanding Chinese Shipbuilding Market Dominance
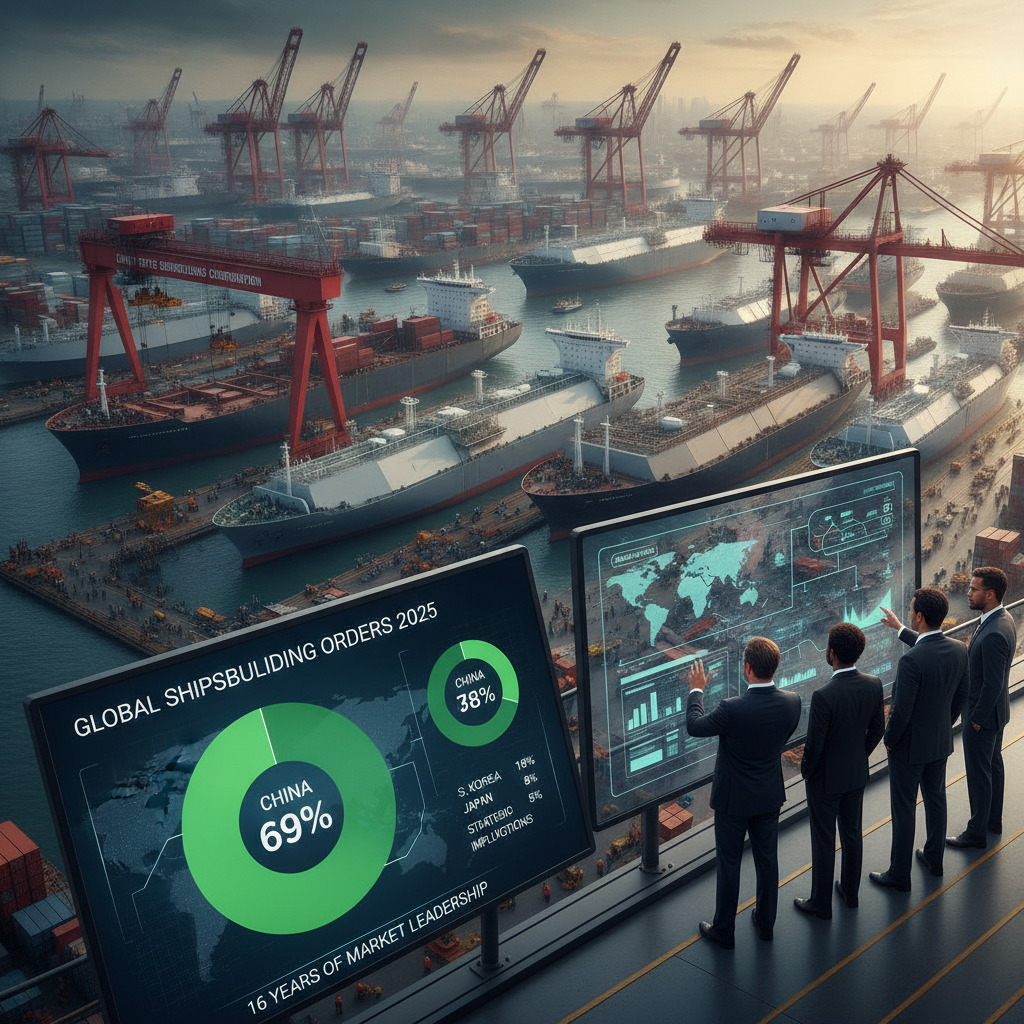
The global maritime landscape is undergoing a massive shift. In recent years, Chinese Shipbuilding Market Dominance has reached unprecedented levels, raising critical questions for logistics and shipping experts worldwide. According to the Ministry of Industry and Information Technology, China maintained its global lead for the 16th consecutive year in 2025, solidifying a formidable market position.
Statistics Behind Chinese Shipbuilding Market Dominance
Data from late 2025 and 2026 reveals exactly how vast this lead has become. The country’s shipbuilding output reached 53.69 million deadweight tonnes (DWT) in 2025, which accounts for 56.1% of the global total. Moreover, recent reports highlight that this market share is accelerating further.
- New orders secured in 2025 reached 107.82 million DWT, representing 69% of the global market.
- Holding orders climbed to 274.42 million DWT, accounting for 66.8% of global order backlogs.
- By September 2026, industry data reported that Chinese shipyards held 64% of the global shipyard order book.
The Future of Chinese Shipbuilding Market Dominance
For logistics professionals, these statistics signal potential supply chain centralization. Chinese shipyards currently boast an average order book equivalent to 4.2 years of capacity. While competitors lag significantly in volume, China’s capacity expansion ensures it will deliver an estimated 44 million Compensated Gross Tonnage (CGT) in 2028 alone. Understanding this trend is now essential for strategic fleet planning.
References
China dominates global shipbuilding orders, report says (2026)
China Remains World’s Largest Shipbuilder In 2025 – Marine Insight
China’s shipbuilding industry extends global lead for 16th consecutive year
China’s shipbuilding sector maintains global lead in 2025
China’s shipbuilding sector maintains global lead in 2025 – China Daily