Will Your China Plus One Supply Chain Survive the 2026 Shifts?
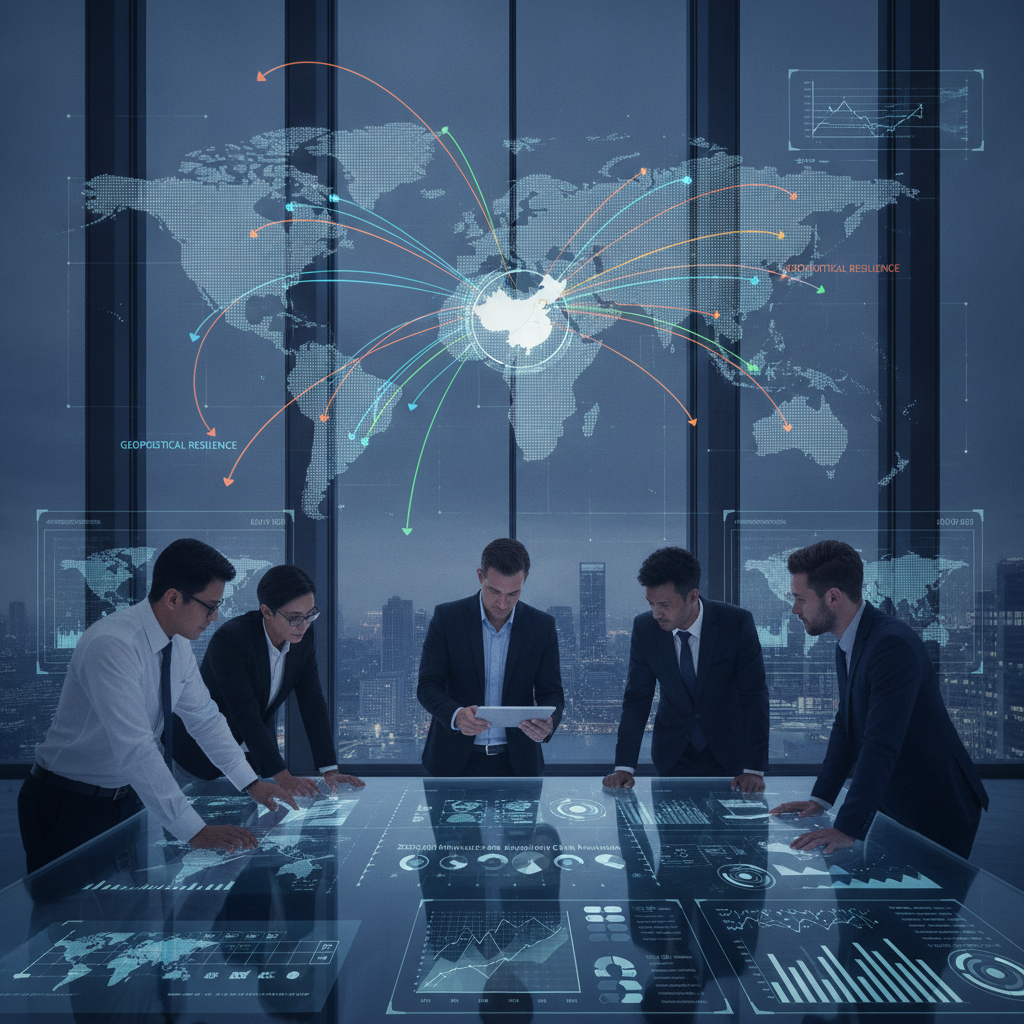
For logistics experts, the China Plus One Supply Chain is no longer just a buzzword; it is a survival mandate. In 2026, the strategy evolved from labor-cost arbitrage into a blueprint for geopolitical resilience. U.S. imports from China plummeted to $308 billion in 2025, a 42% decrease from their 2018 peak. Rather than abandoning Chinese manufacturing, enterprises are rewiring their networks for regional optionality.
Evolving the China Plus One Supply Chain to a Multi-Hub Model
Industry leaders are adopting a multi-hub model. China remains a primary platform for advanced components, while final assembly is distributed globally. This fragmentation triggered a surge in cross-border intermediate goods movement. Consequently, air cargo demand among Asia-Pacific airlines surged by 8.4% year-on-year in 2025.
Key Destinations for the China Plus One Supply Chain
Foreign direct investment (FDI) clearly maps this realignment. Key destinations include:
- Vietnam: Secured $36 billion in FDI in 2025, driven by electronics manufacturing.
- India: Attracted $81 billion in FDI during the 2024-2025 fiscal year.
Furthermore, 91% of surveyed EU manufacturers integrated this framework into their 2025-2026 ESG reporting.
Future-Proofing Your China Plus One Supply Chain
To maintain a competitive edge, building a resilient network requires engineering a dynamic, multi-country ecosystem rather than finding a single backup factory. Rigorous dependency mapping is essential to ensure new suppliers meet global compliance and delivery standards.
References
1. GTsetu: China-Plus-One Strategy Explained (2026). 2. Cello Square: China Plus X White Paper (2026).