The New Reality of the Critical Minerals Supply Chain
For logistics and shipping experts, the Critical Minerals Supply Chain has rapidly evolved from a theoretical vulnerability into a frontline operational challenge. As the global push for electric vehicles and clean energy accelerates, the critical minerals supply chain market is projected to expand to approximately $679.7 billion by 2035, growing at a robust 7.5% CAGR. However, the International Energy Agency (IEA) reported that severe supply chain disruptions became a stark reality in 2025, driven by geopolitical export controls and market concentrations. This shift is forcing shipping professionals to fundamentally rethink procurement routes, inventory buffering, and traceability.
Navigating Critical Minerals Supply Chain Disruptions
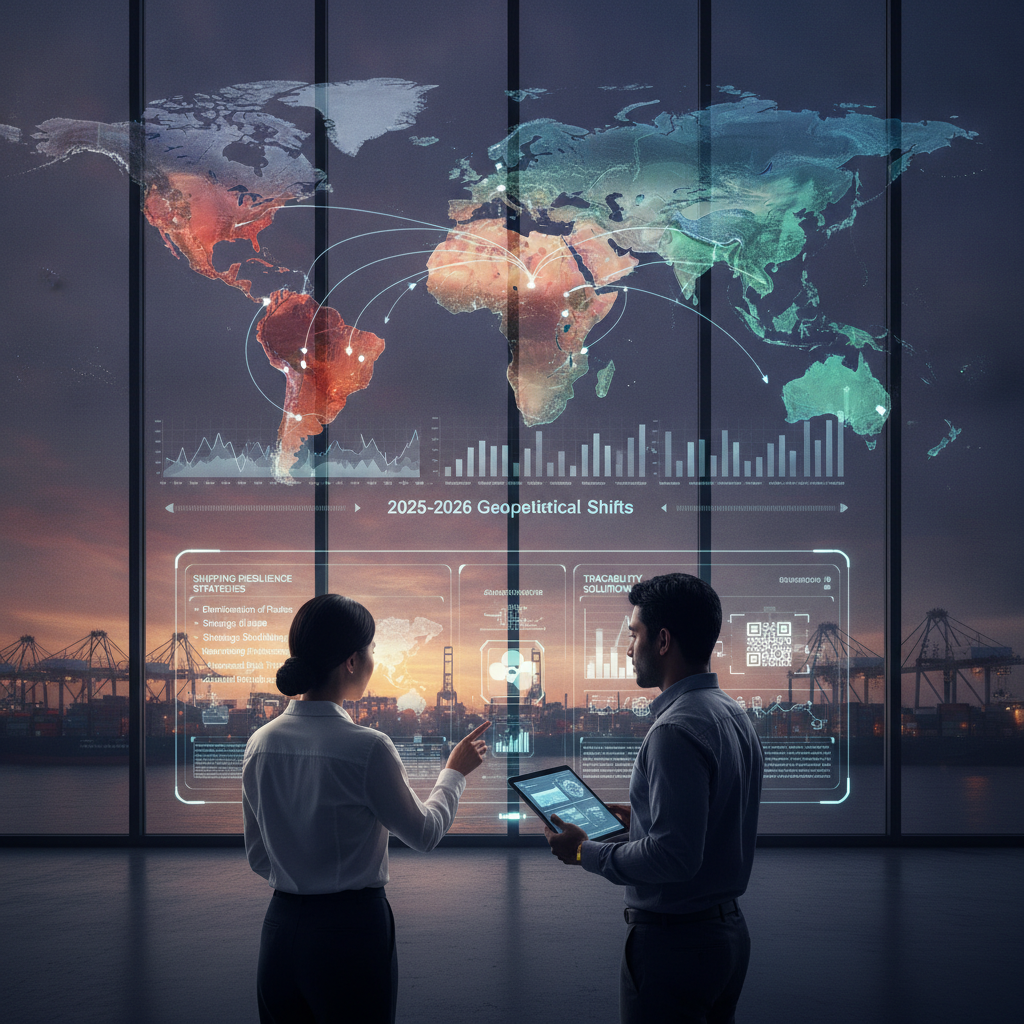
Recent data highlights the immense pressure placed on maritime and overland transport networks. According to UNCTAD, global lithium demand alone is projected to surge by 353% between 2024 and 2040, while graphite demand could rise by 131%. Fulfilling this exponential demand is heavily complicated by geopolitical friction. In 2025, dominant market players introduced major export controls on heavy rare earth elements, significantly disrupting downstream industries and altering traditional shipping lanes. To combat these hurdles, logistics managers are increasingly investing in strategic stockpiling, alternative sourcing regions like Sub-Saharan Africa, and digital tracking technologies.
Building a Resilient Critical Minerals Supply Chain
Governments and corporations are actively intervening to secure trade flows and derisk transit corridors. Key developments reshaping the logistics landscape include:
- International Traceability Mandates: The OECD and global partners are emphasizing enhanced traceability frameworks for minerals like nickel to ensure responsible sourcing and supply resilience.
- Geopolitical Alliances: The 2025 and 2026 Quad Critical Minerals Initiatives between the US, Japan, India, and Australia aim to diversify sourcing and coordinate logistics networks outside of concentrated monopolies.
- Digital Logistics Integration: Billions of dollars are being redirected into midstream processing and specialized logistics, creating a pressing need for transparent, digitalized tracking from mine to manufacturing facility.
Ultimately, securing the Critical Minerals Supply Chain is no longer just a mining or manufacturing problem; it is fundamentally a logistics imperative. Shipping experts who adapt to new traceability standards and diversified routing will lead the next era of industrial transport.
References
J.P. Morgan (2026). The Growing Demand for Critical Minerals. Dimension Market Research (2025). Critical Minerals Supply Chain Market. United States Studies Centre (2026). Operationalising the Quad Critical Minerals Initiative. OECD (2026). Nickel: Enhancing Resilience Through Traceability. Industrial Info Resources (2026). IEA: Global Critical Minerals Risks Became Realities in 2025.