Is Semiconductor Supply Chain Reshoring Rewiring Global Logistics?
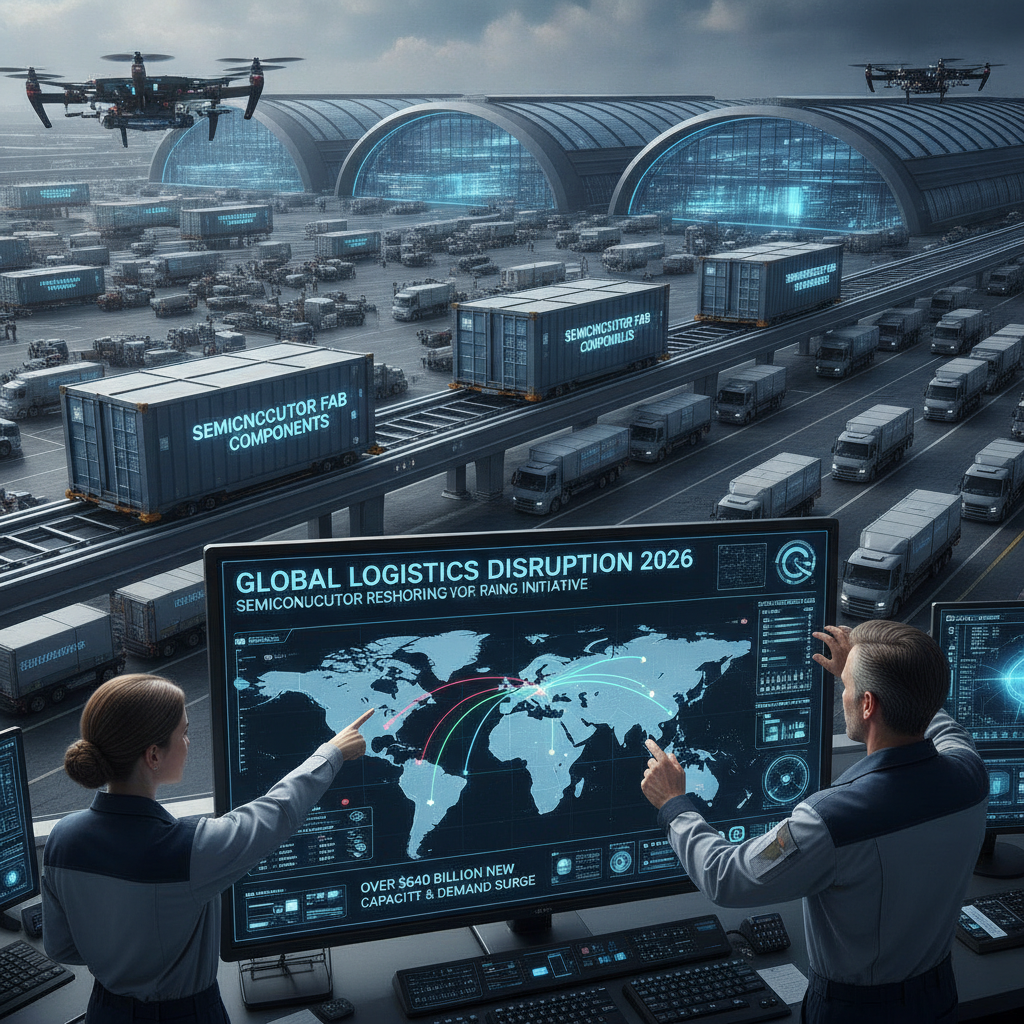
As we navigate 2026, Semiconductor Supply Chain Reshoring is fundamentally realigning global trade routes. Driven by government incentives like the U.S. CHIPS Act, the geographic distribution of chip manufacturing is shifting, introducing both massive opportunities and complex bottlenecks for shipping experts.
The 2026 Fab Construction Boom
The influx of capital into domestic production is staggering. Over $640 billion in domestic fab investments have been announced in the U.S. alone. This infrastructure growth is fueling the electronics parts forward logistics market, valued at $98.4 billion in 2025 and projected to grow at a 6.8% CAGR. Shippers are seeing unprecedented demand for transporting specialized fab construction materials, heavy machinery, and ultra-high-purity chemicals.
Navigating Critical Bottlenecks
Despite massive investments, logistics professionals must prepare for near-term disruptions:
- Extended Lead Times: Semiconductor lead times reached 40 weeks in early 2026, forcing forwarders to optimize inventory buffers.
- Delayed Production: Newly reshored fabs will not achieve volume production until 2028-2030, creating interim reliance on traditional Asian trade lanes.
- Emerging Corridors: Simultaneous “China+N” strategies are boosting logistics networks across India and Vietnam.
Adapting to Semiconductor Supply Chain Reshoring means investing in specialized, high-purity freight capabilities and preparing for a multi-year transitional period.
References
SupplyICs, “The CHIPS Act and Semiconductor Reshoring: What It Means for Component Availability” (July 2026). Dataintelo, “Electronics Parts Forward Logistics Market Size 2025 to 2034” (April 2026). The Chip Reshoring Wave and Asia’s New Semiconductor Hubs (June 2026).